So This Is Ownership: Before You Buy a Laundromat or Gas Station, Find Out Who Does the Work
The machines are running and the pumps are busy. Before treating that as a business that runs itself, follow the people, records, and decisions keeping the operation moving.
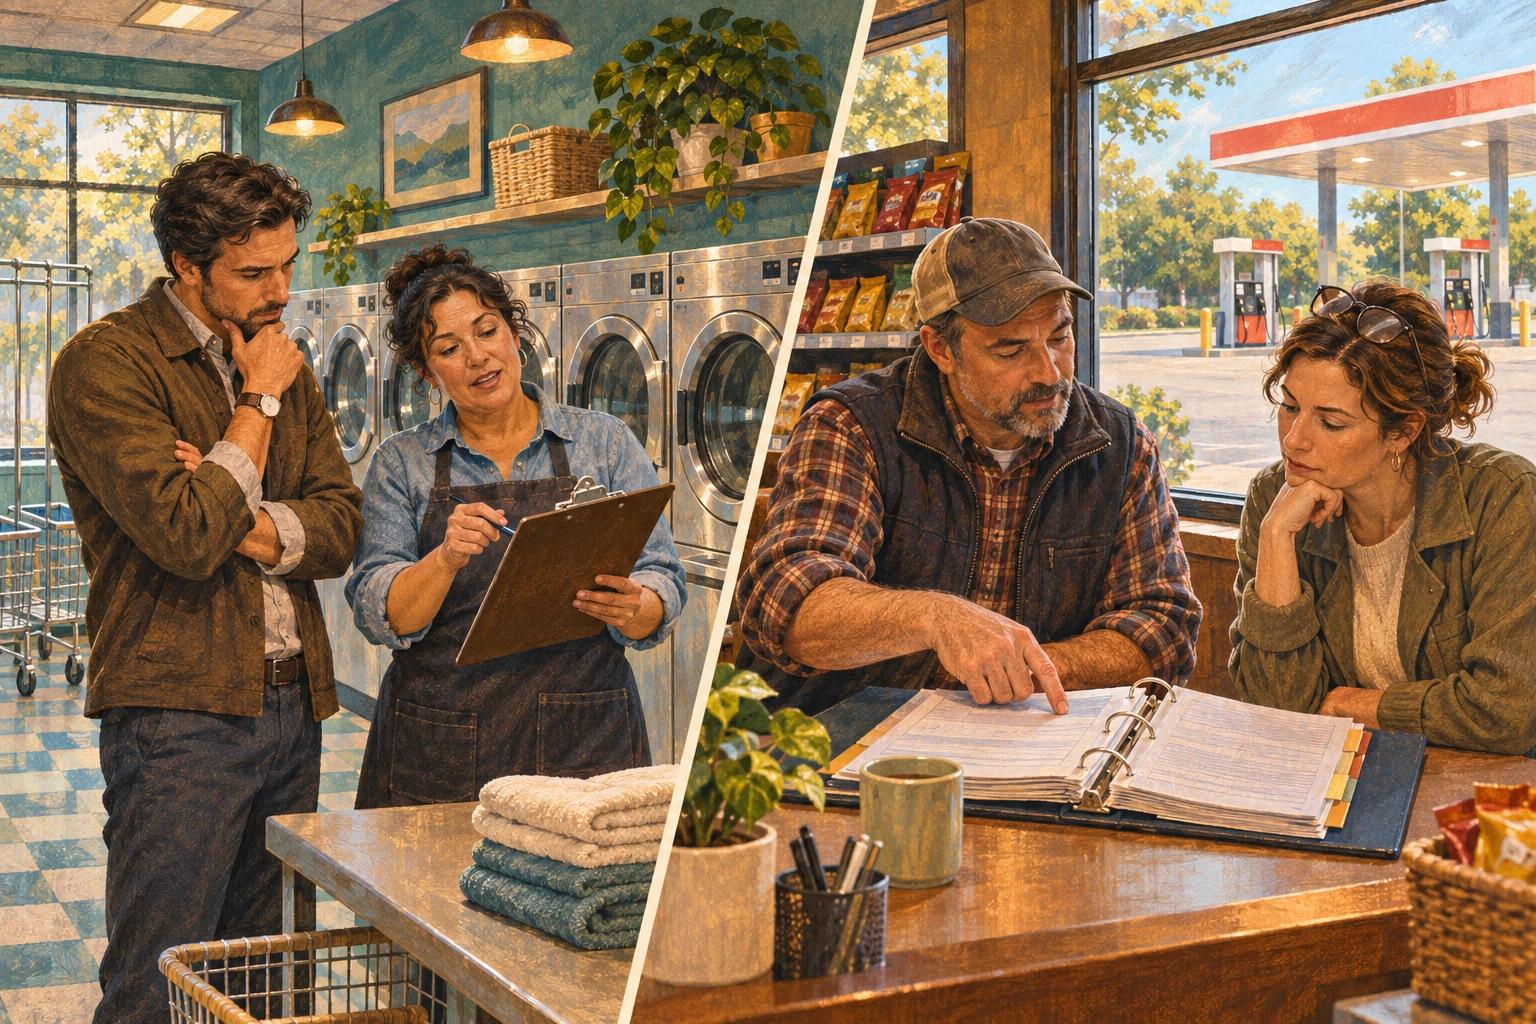
The laundromat is quiet enough to hear the machines turning. A customer folds towels at a table. On a first visit, you can easily notice the equipment and miss the work that happened before you arrived.
At a gas station, the same mistake could happen differently. Customers pay and leave. You can see the sale, while knowing little about the deliveries, records, maintenance arrangements, and decisions behind it.
These are fictional observation scenes, not reports from actual businesses. They introduce a pre-purchase assignment: investigate who does the work before deciding what the operation would ask of you.
Today’s first article examined the “passive income” promise. This companion turns it into evidence requests for two distinct businesses. A laundromat and a gas station need separate assessments; neither label tells you enough to buy.
Start by defining what is actually for sale
Before comparing figures, clarify the proposal with your advisers. Is it an operating business, specified equipment, real property, a leasehold arrangement, or some combination? What is included, excluded, leased, or subject to another agreement?
At a station, identify the proposed roles around the site, tanks, fuel, shop, and any branded arrangements. At a laundromat, identify who owns the installed equipment, which services are offered, and what premises arrangements are proposed.
These are questions for the actual transaction. Do not infer legal responsibility from a listing’s shorthand.
The SBA’s business-buying guidance recommends examining contracts, leases, cash flow, inventory, and the broader operation. Use a transaction lawyer and accountant to determine the investigation appropriate to the purchase. This article adds an operational work map; it does not replace financial, legal, technical, or environmental due diligence.
For the laundromat, follow one machine and one customer problem
Ask to observe an agreed part of the operation with permission. Record the day, time, scope, and limitations. Respect customer privacy and staff responsibilities.
For one installed machine, identify the model, age information available, applicable manual, service history, current condition, and who performs routine checks. Ask for an appropriate qualified inspection rather than treating a working cycle as proof of overall condition.
There is useful manufacturer evidence for asking about recurring work. Dexter’s model-specific dryer maintenance sheet identifies tasks at daily and longer intervals. Use the correct instructions for the actual equipment; the linked sheet is an illustration, not a schedule to apply to every laundromat.
Then trace a customer issue. Use a suitable redacted record or a hypothetical discussion: a payment has been taken, but the requested service has not started. Who receives the report? Who can authorize an appropriate remedy? Who records it? What happens outside an attendant’s hours?
Do not ask staff to demonstrate unsafe faults or attempt technical repairs. You are investigating responsibility and evidence, not performing a maintenance trial.
Map the laundry work beyond the machines
For the proposed service model, ask which tasks occur around opening, cleaning, customer support, payment reconciliation, supplies, closing, and provider coordination. If wash-and-fold or other staffed services are offered, map those separately from self-service use.
Give each task a current performer and a proposed performer after purchase. Identify work the seller does informally and work described as a favor from someone else. Ask what dependable arrangement would replace it.
Request utility records and the relevant lease and equipment agreements through the appropriate process. With your accountant and technical advisers, investigate the operating assumptions and potential work ahead. Do not estimate revenue or machine condition from a brief visit or from utility consumption alone.
Ask about recent downtime and how it was resolved. A useful answer connects the event to a dated record, an appropriate service provider, and a process for communicating with customers. A single example cannot establish future reliability, but it can show you what to investigate next.
For the gas station, add a distinct tank-system investigation
If the site has regulated underground storage tanks, involve an appropriately qualified environmental professional and the relevant regulator early in the proposed purchase. Ask for a review suited to the property, operation, and transaction; no generic checklist establishes that the site is environmentally sound.
The EPA’s UST FAQ describes federal requirements concerning registration, release detection, spill and overfill protection, records, and trained operators. State and local implementation matters. EPA directs owners and operators to the applicable implementing agency; for tanks in Indian country, it directs them to the EPA regional program.
Use that referral to establish what applies to this specific system. Ask your specialists to examine available tank, testing, inspection, maintenance, release, and corrective-action records, and to identify missing evidence. Do not infer compliance from the fact that fuel is currently being sold.
EPA also explains UST financial-responsibility requirements. Have the relevant advisers assess the mechanism, coverage, and costs applicable to the proposed ownership. A general insurance description is not proof that the intended arrangement meets the requirements.
Find the people behind the station’s ordinary day
For the actual station, ask who handles customer issues, shop work if present, fuel-delivery coordination, equipment problems, required records, and escalation. Which roles need particular training? What happens when the scheduled person is unavailable?
Trace an alarm or suspected problem through a discussion of the site’s established procedures with qualified personnel. Ask who receives it, who has authority, and how action is documented. Do not improvise a response or conduct a live emergency test as a prospective buyer.
Check what the owner reviews personally. A service company may perform a defined task while the business still needs someone to schedule it, receive the report, resolve a finding, or arrange payment. Ask for the actual scope and responsibilities rather than assuming “contracted out” means fully handled.
If the shop includes food or other regulated offerings, obtain advice on those activities separately. The tank review cannot settle every requirement of the whole business.
Use one evidence register, with separate industry sections
For each business you consider, keep this register. Do not combine two sites’ records or treat one seller’s arrangement as typical of an industry.
Question
Evidence to investigate
Your proposed arrangement
Who performs recurring work?
Task records, role descriptions, appropriate observation
Name the role, availability, and cost
Who handles exceptions?
Suitable past examples and response procedures
Specify first contact, authority, and fallback
What condition is the equipment in?
Relevant records and qualified assessment
Identify unresolved work and quotations needed
What agreements support operation?
Adviser review of applicable documents
Identify required new arrangements or consents
What obligations apply?
Specialist and authority review for this site
Record who is responsible and what remains unresolved
What does the seller personally contribute?
Walkthrough of ordinary and less frequent tasks
Decide what you will do or replace
Add the source, date, outstanding question, and next action to each entry. Keep “seller says,” “document reviewed,” “professionally assessed,” and “still unknown” as distinct statuses.
Rebuild the operating picture around your own role
Bring the owner-role statement from Day 9 and the handover register from Day 10. Put the work you expect to do beside the time you can offer. Ask where you would be the fallback, and whether that arrangement fits your life.
With an accountant, examine historical records and build a forecast reflecting your proposal. Include researched staffing and service costs, immediate work, ongoing commitments, and the timing of receipts and payments. Investigate equipment-replacement and downtime scenarios without presenting a guessed allowance as an established cost.
If the plan relies on a manager, establish a credible role and budget. If it relies on you, make your work visible. A business may still interest you after that exercise. The result should be an honest operating plan rather than an attractive figure disconnected from who keeps the place running.
Finish the visit with sharper questions
At the fictional laundromat, the turning machines tell you that customers are using them now. You still need to know who prepares, checks, cleans, responds, and plans.
At the fictional station, customers leaving the pumps tell you that transactions are occurring. You still need appropriate evidence about the operation and its obligations.
Before proceeding, choose the unresolved matters that could change your decision. Give each an evidence request and the right person to assess it. An essential unanswered question can justify pausing rather than turning uncertainty into confidence.
The next step in this YupUp.ai series is narrowing your options. Tomorrow, we will turn a long list into three ideas worth deeper investigation—and prepare useful questions for owners before savings are committed.
Need a review and local marketing system?
YupUp helps independent businesses manage reviews, local visibility, and customer follow-up with AI-assisted workflows.
Get a free growth review